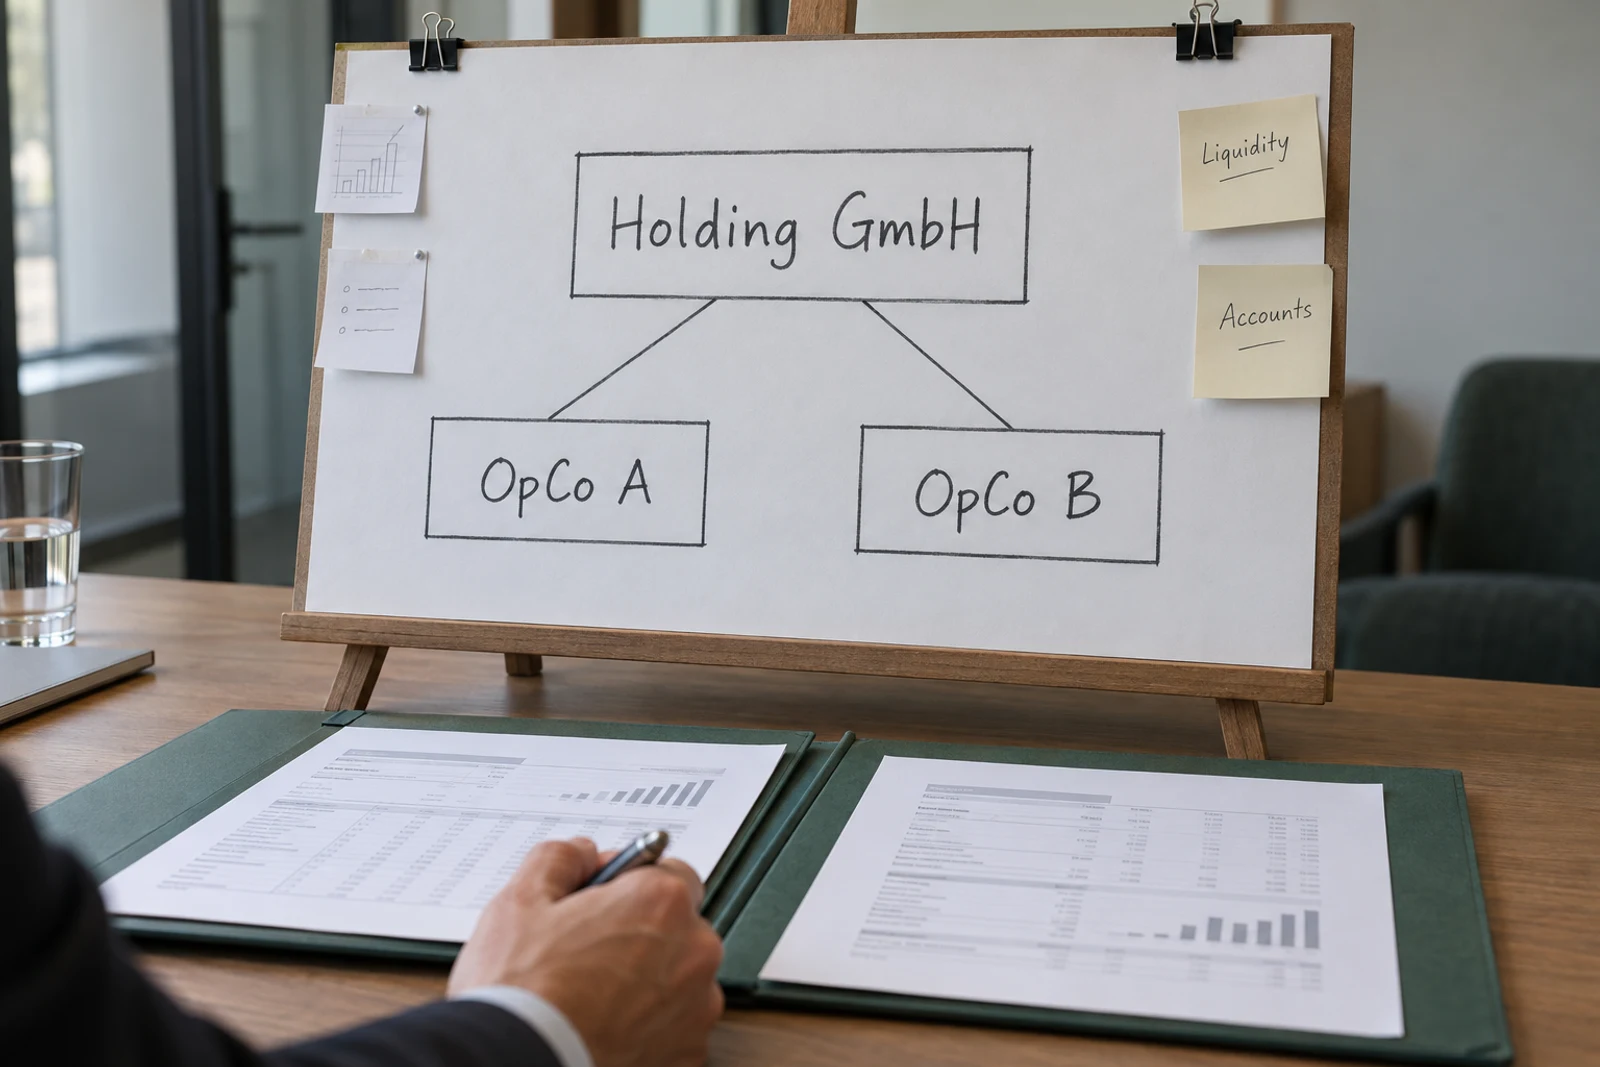
An additional company can organise a business group, while also creating new administrative work. Whether a holding company makes sense depends on ownership objectives, business activities and planned changes, rather than a universal profit threshold.
What specific function should the holding company perform? Possibilities include consolidating investments, preparing for further acquisitions or clarifying ownership.
Arrow = named dependency+ Select a record
Scroll to move through chapters. Select a record to examine the connection.
What specific function should the holding company perform? Possibilities include consolidating investments, preparing for further acquisitions or clarifying ownership. State the objective without tax slogans. If several owners are involved, compare their expectations explicitly. Different views on distributions, growth and a future sale do not disappear simply because another entity sits between the owners and the operating business. Resolve those expectations before designing the structure.
Test the structure in daily use
Draw the ownership relationships, money flows and responsibilities. Who makes investment decisions, who invoices for services and which entity needs liquidity? Add recurring costs for bookkeeping, accounts, agreements and coordination. Obtain specific legal and tax assessment of the intended transactions. An organisation chart becomes useful only when day-to-day processes and the information needed to support them are arranged in an understandable way.
Consider change and exit
Consider not only planned growth, but also a business disposal, the arrival of new owners or eventual simplification. Review the potential consequences of these changes with advisers. Keep a written record of the assumptions behind the decision. A well-founded holding structure serves a real commercial purpose and can be reviewed regularly for continuing usefulness, rather than being understood solely as a permanent promise of savings.
JABA / PERSPECTIVES
Jaba supports commercial decisions. Individual legal and tax advice is provided exclusively by separately engaged, appropriately qualified professionals.