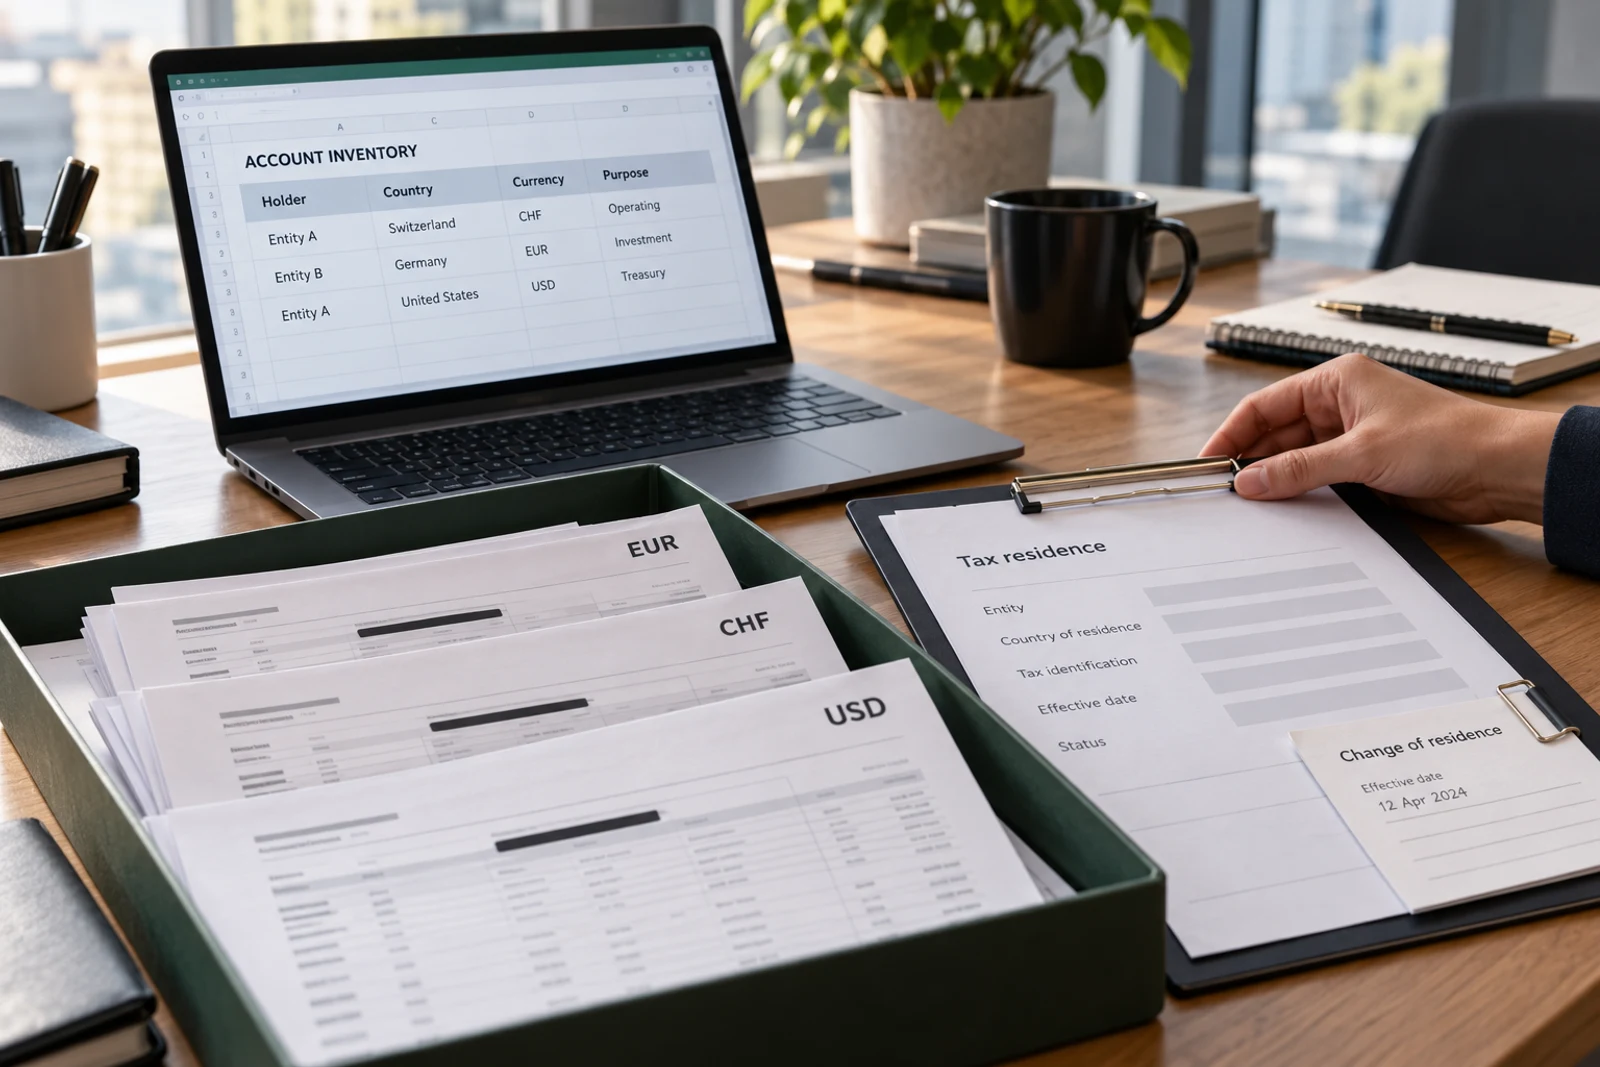
The Common Reporting Standard provides for international exchange of certain financial account information. For business owners operating across borders, it is a reason to keep accounts, entities and tax-residence information consistently documented.
List banking and financial accounts by holder, entity, country and purpose. Record who has access and where supporting documents are stored. Forgotten accounts from older projects often create more confusion than actively used accounts. A simple inventory makes discussions with accounting teams easier and shows which information might disappear when a director or adviser changes. Include closed accounts in the historical record where relevant.
Identify inconsistencies early
Compare the information supplied to banks with the records held by tax advisers. Changes of address, ownership or responsibility should not be corrected in just one isolated form. Record when a change took place and which documents support it. The reporting and updates required in a particular case need professional assessment based on the countries, accounts and people involved.
Assign lasting responsibility
Assign someone to add new accounts and periodically check the inventory for completeness. The practical benefit is an understandable business organisation, rather than any assumption that overseas activities are invisible. Where historical information is unclear, assemble the facts before qualified advisers assess the next steps. Unverified promises of automatic tax exemption provide no sound basis for making decisions.
JABA / PERSPECTIVES
Jaba supports commercial decisions. Individual legal and tax advice is provided exclusively by separately engaged, appropriately qualified professionals.